
Innovative financing models for global sanitation projects are reshaping how cities, utilities, development banks, and private operators deliver one of the most essential public services in the world. Sanitation includes the systems that safely contain, transport, treat, and reuse human waste, wastewater, and related sludge. In practice, that means everything from household toilets and sewer networks to fecal sludge treatment plants, decentralized wastewater systems, and reuse infrastructure that turns waste into water, energy, or fertilizer. I have worked on sanitation funding discussions where technically sound projects stalled for years not because the engineering was weak, but because the capital stack, tariff structure, and risk allocation were wrong from the start.
This matters because sanitation is both a health intervention and an economic platform. The World Health Organization has long linked inadequate sanitation to diarrheal disease, stunting, and broader public health costs, while the World Bank and UNICEF have shown that poor sanitation reduces productivity, harms school attendance, and increases environmental degradation. Yet sanitation has historically received less investment than water supply or energy because revenue is fragmented, benefits are dispersed across health and environment budgets, and many assets are politically difficult to price. Global opportunities in sanitation therefore depend on financing innovation as much as technical design. The strongest projects combine public finance, concessional capital, commercial discipline, and measurable service outcomes.
As a hub topic, global opportunities in sanitation extend beyond building toilets. They include urban wastewater treatment, climate-resilient drainage interfaces, resource recovery, digital utility management, circular economy ventures, and public-private delivery models adapted to local affordability. A useful way to define innovative financing is simple: any structure that brings more capital into sanitation, lowers the cost of capital, allocates risk to the parties best able to manage it, or rewards verified results. That can include blended finance, municipal bonds, outcome-based contracts, microfinance for households, carbon-linked revenues, and pooled facilities for smaller utilities. Understanding these models helps governments and investors move sanitation from a donor-dependent expense to a bankable, scalable public service.
Why sanitation financing is uniquely difficult
Sanitation projects are hard to finance because cash flow rarely aligns neatly with social value. A sewerage system may prevent disease outbreaks, increase land values, and reduce river pollution, but those benefits accrue to households, health systems, tourism businesses, and downstream users rather than only to the utility that built it. In many low-income and middle-income markets, user tariffs do not cover operating costs, let alone debt service and lifecycle renewal. Informal settlements may lack legal connections, property records, or billing addresses. Fecal sludge operators often work in fragmented markets with weak regulation and unpredictable disposal behavior. From a lender’s perspective, that creates demand risk, collection risk, governance risk, and political risk all at once.
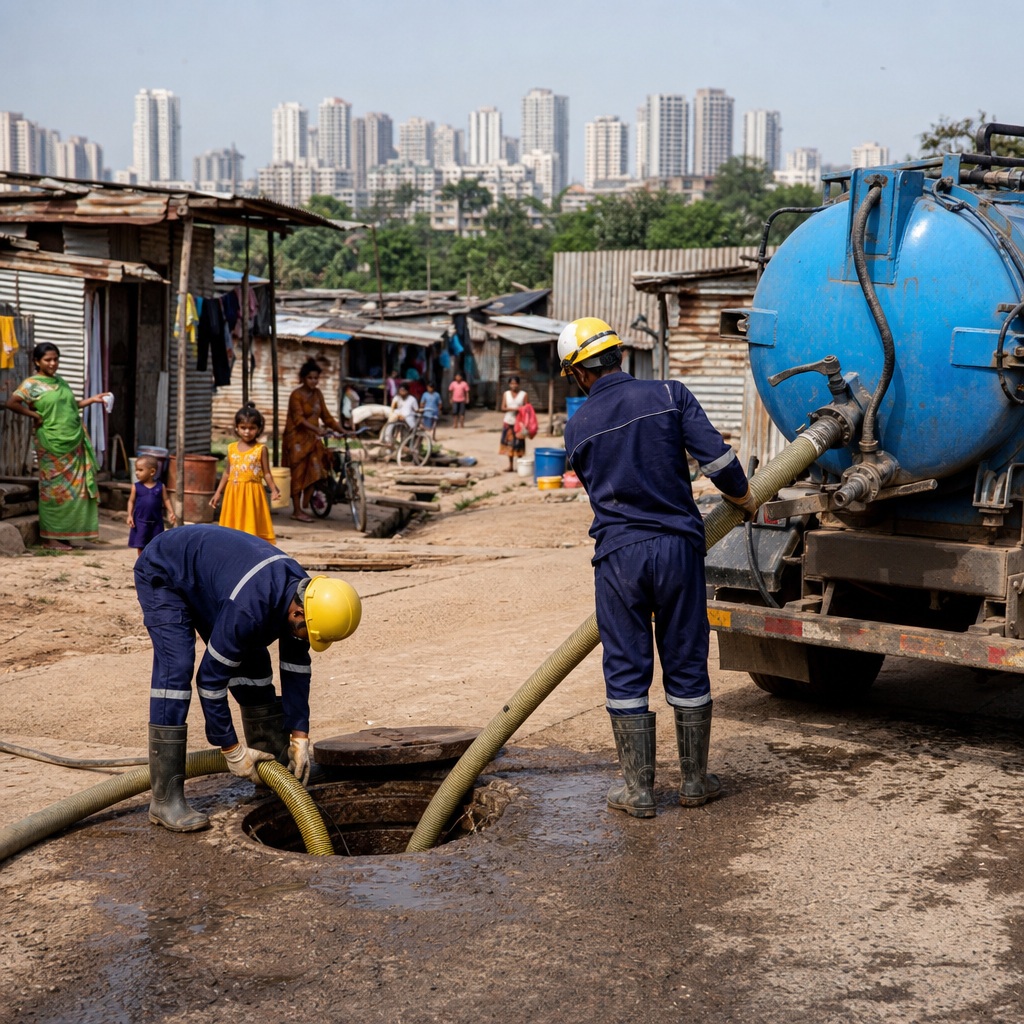
Sanitation also requires patient capital. Networked sewer systems can take years to plan, permit, construct, and connect. Treatment plants need reliable power, trained operators, laboratory compliance, and sludge management. Decentralized systems can be cheaper and faster, but they still need scheduled desludging, service contracts, and enforcement mechanisms to prevent illegal dumping. I have seen projects where capital grants funded construction but no one ring-fenced operating expenditure, causing assets to deteriorate within two budget cycles. Financing innovation matters because it can cover the full service chain, not just the visible construction phase.
Blended finance as the core model for scale
Blended finance is the most important model for expanding global sanitation because it combines concessional and commercial capital in a way that improves project viability without masking performance. In sanitation, concessional money usually absorbs early-stage risk, funds public-good components, or provides guarantees, while commercial lenders finance portions of infrastructure with clearer repayment sources. Development finance institutions such as the International Finance Corporation, the African Development Bank, and the Asian Development Bank have all supported structures where grants pay for project preparation, public connections, or viability gap support, while loans finance treatment plants, pumping stations, and service expansion.
The practical strength of blended finance is that it can match financing tools to specific bottlenecks. A city may need a grant for low-income household connections, a sovereign or municipal loan for trunk infrastructure, and a performance-based contract for treatment plant operations. That is better than forcing one instrument to solve every problem. In one common structure, donor-funded technical assistance improves utility billing, asset management, and non-revenue water controls, making the sanitation utility more creditworthy before debt is issued. The lesson from experience is clear: blended finance works when concessional capital is targeted, temporary, and tied to reforms rather than used as a permanent substitute for sound utility economics.
Public finance, tariffs, and municipal creditworthiness
Despite the attention given to private capital, public finance remains the backbone of sanitation investment. Taxes, intergovernmental transfers, and utility revenues still fund most sanitation assets globally. The opportunity is not to replace public finance but to make it more strategic. Creditworthy municipalities can issue bonds, access domestic banks, or borrow from national development facilities when they have audited accounts, predictable transfers, and ring-fenced revenue streams. Cities such as Johannesburg and Ahmedabad demonstrated years ago that municipal borrowing becomes possible when governance, disclosure, and financial management improve. Sanitation projects benefit especially when revenues from property taxes, betterment levies, or service charges are linked to long-term capital planning.
Tariff design is central. Full cost recovery from poor households is often unrealistic and inequitable, but zero or symbolic tariffs undermine operations and future borrowing. Better models use increasing block tariffs, targeted subsidies, sanitation surcharges on water bills, cross-subsidies from higher-income users, and transparent budget transfers for social obligations. The point is not to maximize tariffs; it is to create reliable, predictable cash flow. Lenders and operators need to know who pays, when, and under what legal authority. If a municipality cannot answer those questions, it does not yet have a finance problem alone; it has a governance problem.
Outcome-based finance and results-linked contracts
Outcome-based finance ties funding to verified service delivery rather than inputs. Instead of paying simply for pipes or toilets installed, the funder pays for households connected and using services, fecal sludge safely treated, or effluent quality meeting discharge standards. This model is well suited to sanitation because too many projects have historically measured success by construction completion while ignoring functionality. Results-based financing supported by the Global Partnership for Results-Based Approaches and other facilities has shown that verification can sharpen incentives for both public and private providers.
In practice, verification must be designed carefully. If payment depends only on connection numbers, utilities may prioritize easy neighborhoods and ignore informal settlements. If payment depends only on lab compliance, operators may game sampling schedules. The best contracts use a balanced scorecard including continuity of service, safe treatment, customer satisfaction, and affordability protections. Development impact bonds and social impact structures have been discussed for sanitation, but they remain niche because transaction costs are high. Even so, the broader principle is durable: pay for outcomes that matter, verify them independently, and define failure clearly before the contract begins.
Household finance, microcredit, and inclusive sanitation markets
Many of the biggest sanitation gains come from household-level investment, especially in areas not yet served by sewers. Microfinance institutions, savings groups, and pay-as-you-go providers can help families finance toilets, septic upgrades, and connection fees. Water.org’s WaterCredit model is one of the best-known examples, working through local financial institutions to extend small loans for water and sanitation improvements. These loans succeed when products match household cash flow, repayment schedules fit informal income patterns, and technical standards are clear enough to prevent unsafe construction.
Inclusive sanitation finance also supports small and medium enterprises across the service chain: emptiers, transporters, toilet manufacturers, treatment operators, and reuse businesses. I have seen local desludging markets expand rapidly once municipalities introduced licensed dumping points and digital dispatch systems that reduced illegal disposal. Small grants or first-loss facilities can crowd in working capital from domestic banks for these operators. The opportunity here is global but intensely local in execution. Financing must reflect settlement form, land tenure, and customer behavior, because a peri-urban pit-emptying enterprise does not face the same economics as a central-city wastewater utility.
Resource recovery, climate finance, and circular revenue streams
One of the most promising global opportunities in sanitation is resource recovery. Wastewater and sludge can generate biogas, biosolids, compost, reclaimed water, and in some cases nutrients such as struvite. These revenues rarely finance an entire project on their own, but they can materially improve bankability and lifecycle economics. Utilities in cities including Durban and Stockholm have demonstrated versions of energy recovery and reuse, while industrial clusters increasingly purchase treated wastewater for non-potable applications where freshwater is scarce. The bankable insight is that sanitation assets can produce multiple value streams if offtake agreements, quality standards, and operating discipline are in place.
Climate finance is becoming more relevant as methane emissions from wastewater and sludge gain attention and as resilient sanitation infrastructure becomes a climate adaptation priority. Green bonds, sustainability-linked loans, and climate funds can support projects that reduce emissions, conserve water, or improve flood resilience. However, sanitation sponsors should be realistic. Carbon revenues are volatile, measurement can be complex, and certification costs may outweigh benefits for smaller facilities. Climate-linked funding is most effective when it supplements a solid base case rather than rescuing a weak one.
Choosing the right financing model for context
No single model fits every sanitation project. The right structure depends on asset type, service model, institutional maturity, and affordability constraints. The comparison below shows how common financing approaches align with typical sanitation use cases.
| Financing model | Best use case | Main advantage | Main limitation |
|---|---|---|---|
| Public budget and transfers | Core public infrastructure, low-income service expansion | Can fund broad social benefits and unprofitable areas | Vulnerable to political cycles and budget pressure |
| Blended finance | Large urban systems, utility reform, treatment assets | Lowers risk and attracts additional capital | Complex structuring and long preparation timelines |
| Municipal or green bonds | Creditworthy cities with stable revenue | Access to long-term capital at scale | Requires strong disclosure and financial management |
| Results-based finance | Connections, treatment performance, non-sewered services | Rewards verified outcomes, not just construction | Needs rigorous monitoring and independent verification |
| Microfinance and SME lending | Household toilets, septic upgrades, small operators | Reaches underserved customers quickly | Loan sizes are small and technical oversight is essential |
The most successful sanitation programs often layer these models. A national grant may finance trunk assets, a municipal bond may fund expansion, households may borrow for toilets or connection fees, and operators may earn bonuses for verified treatment compliance. That is how sanitation moves from isolated projects to citywide inclusive service.
What project developers and policymakers should do next
For governments, the first priority is project preparation. Bankable sanitation pipelines require feasibility studies, demand analysis, environmental and social safeguards, tariff scenarios, land and permit clarity, and realistic operations planning. Too many proposals jump straight to construction budgets without proving service economics. Standardized contracts, utility benchmarking through tools such as the International Benchmarking Network, and digital performance reporting can materially improve investor confidence. National governments should also create pooled financing windows for smaller municipalities that cannot access capital markets individually.
For investors and philanthropies, discipline matters as much as ambition. Fund the weakest link in the value chain, not the most visible asset. If treatment exists but collection fails, invest upstream. If toilets exist but sludge is dumped illegally, finance enforcement, transfer stations, and licensed disposal. If affordability is the barrier, subsidize connections rather than recurring inefficiency. The global opportunities in sanitation are real because demand is structural, urbanization is accelerating, water stress is rising, and public health returns are immediate. The winning financing models are those that treat sanitation as a service business with public-good characteristics, not as a one-time construction event.
Innovative financing models for global sanitation projects work best when they match money to measurable service outcomes, institutional capacity, and long-term operations. Sanitation is not difficult because the sector lacks proven technologies. It is difficult because benefits are shared, revenues are uneven, and project sponsors often underprice maintenance, governance, and customer behavior. The strongest financing approaches therefore combine public commitment with commercial rigor. Blended finance reduces risk where markets are immature. Municipal finance scales infrastructure where governance is credible. Results-based contracts improve accountability. Household and SME finance extend services into places that large utilities cannot reach quickly. Resource recovery and climate-linked instruments add upside when fundamentals are already sound.
For readers using this page as a hub for global opportunities in sanitation, the central takeaway is practical: bankable sanitation depends on the full service chain, from household access to safe treatment and reuse. Every financing decision should start with three questions. What outcomes are being purchased? Who carries each risk? Which revenue sources are truly reliable over the asset life? When those answers are clear, more capital can flow and better projects can be built. Review your current sanitation pipeline, identify the financing gap at each stage, and structure the capital stack to support lasting service, not just construction.
Frequently Asked Questions
What are innovative financing models for global sanitation projects?
Innovative financing models for global sanitation projects are funding approaches that go beyond traditional public budgets, donor grants, or standard utility borrowing. They are designed to unlock new sources of capital, spread risk across multiple stakeholders, and better match how sanitation systems actually generate social, environmental, and economic value over time. In sanitation, this can include blended finance structures that combine concessional funding with private investment, results-based financing that pays providers after verified service outcomes are achieved, public-private partnerships for construction and operations, green or sustainability-linked bonds, microfinance for household toilets and onsite systems, revolving funds, climate finance, and pay-for-performance contracts tied to treatment, reuse, or service expansion.
These models matter because sanitation infrastructure often has high upfront costs, long payback periods, and benefits that are not always captured directly in user fees. A wastewater treatment plant, sewer expansion project, or fecal sludge management system can reduce disease, protect water resources, improve urban resilience, and support economic productivity, but those broader gains may not immediately appear on a utility balance sheet. Innovative financing helps bridge that gap by bringing in actors such as development finance institutions, commercial lenders, impact investors, municipal governments, philanthropic funds, and local communities under structures that reflect both financial and public health outcomes.
In practical terms, an innovative model might fund networked sewer infrastructure in a city while also supporting decentralized sanitation in low-income or informal areas, using a mix of public subsidies, private operating contracts, and performance incentives. It might also help households finance toilets through small loans, while utilities access larger long-term capital for treatment and transport infrastructure. The common thread is flexibility: these models recognize that sanitation is not one single asset class but a chain of services, from containment and collection to treatment and safe reuse, each with different risk profiles and revenue possibilities.
Why is traditional sanitation funding often not enough to meet global needs?
Traditional sanitation funding has historically relied on government budgets, donor assistance, and in some cases tariff revenue from utilities. While those sources remain essential, they are frequently insufficient to meet the scale of global sanitation needs. Many cities in low- and middle-income countries face rapid urban growth, aging infrastructure, informal settlement expansion, and climate-related pressures at the same time. Building or upgrading sewers, treatment plants, fecal sludge systems, pumping stations, stormwater interfaces, and reuse facilities requires substantial capital, yet municipal budgets are often stretched across multiple urgent priorities such as housing, healthcare, transport, and education.
Another challenge is that sanitation revenues are often weak or politically constrained. User tariffs may be too low to cover full operating and maintenance costs, let alone major capital investment. In many places, collection rates are inconsistent, service areas are fragmented, and utilities may lack the creditworthiness required to attract affordable commercial financing. Sanitation projects also tend to be less visible politically than roads, airports, or power plants, despite their major public health importance, which can make them harder to prioritize in public spending decisions.
There is also a structural mismatch between how sanitation creates value and how it gets paid for. The benefits of sanitation include lower healthcare costs, cleaner waterways, improved school attendance, stronger labor productivity, land value gains, and environmental protection. Yet many of these benefits accrue to society broadly rather than to the sanitation provider directly. As a result, projects that are highly valuable from a public policy perspective can still appear financially weak if judged only by narrow cash-flow metrics. Innovative financing models help address this by combining subsidies with market capital, linking payments to outcomes, monetizing reuse or resource recovery where possible, and designing financial structures that reflect sanitation’s full social and environmental return.
Which financing approaches are most commonly used in sanitation today?
Several financing approaches are increasingly common in sanitation, and the best choice usually depends on the project type, local institutions, and the maturity of the service provider. Blended finance is one of the most widely used models. It combines concessional capital from governments, donors, or development banks with commercial capital from private investors or lenders. The concessional layer can absorb some risk, reduce financing costs, or fund components that are essential but not directly revenue-generating, making the overall project more bankable.
Results-based financing is also gaining traction, especially for projects focused on measurable service delivery outcomes. Under this model, funds are disbursed once agreed results are achieved and independently verified. In sanitation, those results might include the number of safely managed toilets installed, volume of wastewater treated to standard, households connected, or sludge safely emptied and processed. This can improve accountability and encourage performance, though it works best when service providers have enough working capital or bridge finance to operate before payments are released.
Public-private partnerships remain important for larger systems, particularly where private operators can bring technical expertise, operational efficiency, or lifecycle asset management skills. These arrangements can cover design, construction, operation, maintenance, or combinations of those functions. However, successful sanitation PPPs require clear regulation, realistic demand assumptions, transparent contracts, and safeguards to ensure affordability and equitable access. Without those foundations, risk can be misallocated and service outcomes can suffer.
At the household and community level, microfinance and small-scale lending play an important role, especially for toilets, septic systems, and decentralized treatment solutions. These products help families spread upfront costs over time and can be paired with subsidies for the poorest households. Municipal bonds, green bonds, and sustainability-linked debt are also emerging in some markets, especially where cities or utilities have stronger balance sheets and can demonstrate environmental outcomes such as pollution reduction, water reuse, or emissions mitigation. In addition, revolving funds, land value capture, climate adaptation finance, and revenue from by-products such as biogas, compost, reclaimed water, or nutrients can all form part of a broader sanitation financing strategy.
How can sanitation projects attract private investment without compromising public goals?
Sanitation projects can attract private investment successfully when they are structured around clear public policy goals, realistic revenue models, and fair risk allocation. Private capital is generally interested in predictable cash flows, transparent regulation, credible counterparties, and projects that have manageable construction, operational, and political risk. That means governments and utilities need to do more than simply invite investors in. They need to build a project pipeline, improve planning and data quality, define service standards, strengthen contract enforcement, and ensure that financial arrangements support long-term service delivery rather than short-term returns alone.
One of the most effective tools is blended finance. By using grants, guarantees, subordinated debt, viability gap funding, or technical assistance alongside private capital, public and development actors can make sanitation projects more investable while preserving affordability for users. For example, a city might use concessional funds to cover low-income service connections or non-revenue-generating resilience features, while private investors finance treatment assets or operating improvements with clearer revenue streams. This approach helps align public interest objectives with investor requirements.
Safeguarding public goals also requires strong regulation and contract design. Sanitation is a public health service, so access, quality, affordability, and environmental compliance cannot be treated as secondary issues. Contracts should define service obligations clearly, include performance indicators, provide oversight mechanisms, and address what happens if demand projections, tariffs, or operating conditions change. In many cases, public authorities retain responsibility for policy, subsidies, and social protections, while private partners focus on delivery functions where they have comparative advantages.
Importantly, private investment does not need to mean full privatization. In sanitation, there are many middle-ground structures, such as management contracts, lease agreements, build-operate-transfer models, or targeted investments in specific assets like treatment plants, sludge processing, or reuse infrastructure. The strongest projects are usually those that are honest about what can generate revenue, what still requires public support, and how social objectives will be protected for low-income and underserved communities.
What makes a sanitation financing model successful over the long term?
A successful sanitation financing model is one that delivers reliable, inclusive, and environmentally safe services over many years, not just one that closes an initial funding gap. Long-term success depends first on whether the financing structure matches the realities of the sanitation service chain. Household toilets, sewer expansion, decentralized treatment, fecal sludge collection, large-scale wastewater treatment, and reuse systems each have different cost structures, operating needs, and revenue potential. Trying to finance all of them with a single template often leads to poor results. Effective models are tailored, layered, and designed with the full lifecycle of infrastructure and service delivery in mind.
Institutional strength is another critical factor. Even the most creative financing package will struggle if the implementing utility, municipality, or operator lacks the technical, managerial, or financial capacity to deliver. Successful models are typically supported by strong governance, reliable data, realistic demand forecasting, proper maintenance planning, transparent procurement, and credible monitoring systems. Development banks and donors often add value here through technical assistance, project preparation support, and institutional capacity building, which can be just as important as capital itself.
Affordability and equity are equally important. A financing model may look attractive on paper, but if tariffs are set too high, low-income households may remain unserved or disconnect from formal systems. The best long-term structures balance cost recovery with targeted subsidies, cross-subsidization, social tariffs, output-based aid, or public transfers that ensure vulnerable groups are not left behind. Sanitation systems are most effective when they are universal or close to it